EU wants to tap citizens' savings. Easier said than done / Photo: © AFP/File

 Israel elections chief says inquiry into irregularities will not undermine result
 Vacherot beats Lehecka to clinch Basel title
 Buzzy Holmes doc wins slow Halloween box office in N. America
 Mbappe strikes after China controversy as Real Madrid beat Santander
 Almgren makes triumphant marathon debut in New York
 Chinese state TV fails to air Real Madrid match after Mbappe row
 France launches 'attempted murder' probe after petrol bomb attacks on security forces
 Bayern's Saibari sidelined after ankle surgery
 France launches 'attempted murder' probe after petrol bomb attack on security forces
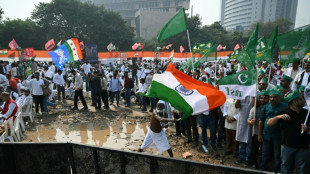
 Tens of thousands protest in India's capital against voter roll revision
 Irish European athletics champion Ciara Mageean dies aged 34
 Seifert blasts 93 as New Zealand win fifth India T20
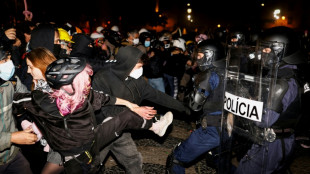 Portuguese police clash with housing protesters, arrest 13
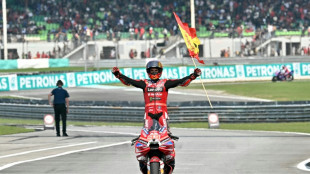
 Marquez wins in Malaysia to stand on brink of MotoGP world title
 Binance says resuming withdrawals after major hack
 Divided Bulgaria votes in tense presidential runoff
 Trump says US looking 'closely' at report Nvidia CEO target of China spy plot
 Maxey scores 38 to lead Sixers 'fighters' to another comeback win
 Valkyries defeat Dream to capture first WNBA crown
 'Seen and heard': Uruguay neighborhood places hopes in pope
 Spewing US election falsehoods, AI chatbots face scrutiny
 EU's new levy on parcels kicks in
 Ocon denies reports of altercation after being dumped by Haas
 Hamilton says love of racing keeps him young
 'Disgraceful' Australia face reckoning after South Africa humbling
The idea sounds simple: tap trillions of euros of EU citizens' savings to unlock capital for European companies through a more integrated financial market.
Getting over the finish line, however, has been complicated, with EU states unable to agree and the idea languishing for years.
More than a decade after the European Union first floated the idea of a deeper capital market, the issue has come roaring back into the spotlight -- and with it the type of concern that dogged previous efforts.
The renewed impetus stems from fears the EU is lagging dangerously behind the world's two biggest economies, the United States and China -- one of the topics set to dominate a summit of the bloc's leaders this week.
Some, including European Commission President Ursula von der Leyen, have raised the prospect of several EU states moving forward, leaving others behind, to establish a Savings and Investments Union.
A key element of such a union is centralising market supervision, an issue pitting the EU's six biggest economies against smaller countries.
France, Germany, Italy and three others say the move is necessary, but Luxembourg and Ireland have expressed reservations.
The topic will be discussed in depth when EU leaders meet Thursday.
But what really does the EU want, and can it be achieved?
- What is the plan? -
The idea first appeared as the "Capital Markets Union" when then-president of the commission Jean-Claude Juncker raised it in 2014.
Now the EU prefers the phrase "Savings and Investments Union" -- which combines the Capital Markets Union and the Banking Union.
Brussels wants to unify national financial markets to make investments flow more seamlessly across the EU.
The commission also wants markets to provide more attractive financial instruments to European citizens, who are more fearful of investing in stock markets than their American counterparts.
Currently, 10 trillion euros ($11.6 trillion) of EU citizens' savings are held as bank deposits, according to the bloc's executive, because people see it as safe.
The reform push is also about giving better access to money for businesses.
By harmonising financial markets and getting rid of the fragmentation that hinders pooling vast capital, there could be much bigger sums available for scale-ups and infrastructure, experts say.
"That is one of the key disadvantages the EU is facing compared to the US and China," said analyst Philipp Lausberg of the European Policy Centre think tank.
- Why is this a hot topic again? -
Europe needs money -- lots of it.
A landmark 2024 report estimated the EU's additional investment needs at 750 billion to 800 billion euros annually.
The EU needs to plough more money into its digital and green transitions as well as defence, faced with rising global instability.
Leaders are keen to move fast.
They agreed in February they wanted "to be done with phase one of the Savings and Investment Union, that includes the market integration, the supervision and the securitisation, by June", von der Leyen said.
Without "sufficient progress", she warned willing EU states would press on alone.
Under EU rules, at least nine countries could go full steam ahead on the project without others.
- Is it popular? -
In theory, member states all support the idea.
In practice, there are strong divisions over how it should look.
A group of countries known as "E6" -- France, Germany, Italy, Spain, the Netherlands and Poland -- want the Paris-based European Securities and Markets Authority to become the EU's supervisor of large stock exchanges.
Irish Finance Minister Simon Harris recommended "enhancing" its role instead.
The business community supports the Savings and Investments Union, including Europe's biggest organisation representing firms, BusinessEurope.
Others, while welcoming deeper financial markets, are more cautious.
Julia Symon, head of research and advocacy at NGO Finance Watch, said key barriers need to be removed if Europe wants a "regime comparable to the US, currently the main destination of EU private capital outflows".
This would mean "joint supervision, harmonised insolvency and greater tax coherence, which go far beyond what is currently proposed", she told AFP.
"The goal should not be to expand finance for its own sake, but to ensure that finance serves long-term economic resilience and productive investment."
A.Kunz--VB