China's Xi calls for stronger fintech oversight, security / Photo: © AFP/File

 Devan Ekambaram and Susha’s 'Varuvaaiy' Makes History as First Tamil Song Nominated for a Grammy
 Miranda Lambert Leads North Texans with Seven Grammy Nominations for 2027
 DiDi Advances Robotaxi Operations in China with New R2 Vehicle and Expanded Safety Infrastructure
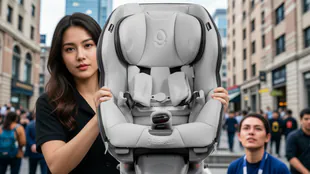 Smart Car Seats Tested: Do Sensors and Apps Actually Improve Safety?
 5 Strategies for Fort Worth Households to Reduce Summer Electricity Costs
 Central Bank of Malta Links Energy Subsidies to Middle East Conflict and Price Volatility
 Shomari Figures Defies Redistricting in Alabama Amid Disaster Relief Crisis
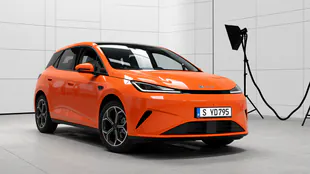 BYD Dolphin G Leasing Deal: Plug-in Hybrid Supermini Available from £174 a Month
A high-level Chinese government meeting led by President Xi Jinping has called for stronger oversight and better security in financial tech, state media reported, with the sector hit hard by a regulatory crackdown.
The government action has pummelled some of China's biggest tech firms, wiping out hundreds of billions of dollars in market value since last year.
But with the Chinese economy hammered by Covid lockdowns, the government has rolled out a series of support measures, including a call for "predictable" tech regulation.
"Regarding large payment and fintech platform enterprises, Xi called for efforts to improve regulations, strengthen institutional weak links, ensure the security of payment and financial infrastructure, and guard against and defuse potential systemic financial risks," according to a readout of the Wednesday meeting by the official Xinhua news agency.
The Chinese leader also "called for these enterprises to be better supported in serving the real economy", Xinhua said.
The officials at the meeting discussed promoting the "healthy development" of fintech companies, it added, and said "China will tighten oversight" of financial holding firms and internet financial services.
Investors have been heartened in recent weeks by similar statements by the Chinese government, with some perceiving them as signals that the tech crackdown is finally easing.
Hopes also soared this month when dozens of new video games were approved, and tech stocks rose on reports that authorities were wrapping up a cybersecurity probe into ride-hailing giant Didi.
But regulators this month denied reports that they were discussing the potential revival of Ant Group's scuppered IPO, which would have been the world's largest public offering at the time.
Ant Group -- the payments affiliate of e-commerce giant Alibaba -- had its share offering cancelled at the last minute in 2020.
Alibaba was later hit with a $2.75 billion fine over alleged unfair practices.
Ant Group is set to apply for a financial licence as soon as this month, Bloomberg News reported Wednesday, citing unnamed people familiar with the matter.
R.Adler--BTB