Britain cedes control of bailed-out NatWest bank / Photo: ©

 Tunisia says 2026 summer hottest on record
 England's Rashid out of Sri Lanka ODIs with hand injury
 Houthis accuse Saudi Arabia of deadly strikes as thousands flee
 Stocks climb as oil slides, AI buzz returns
 India cricketers win in style as Afghan savours 'special' Games silver
 La Liga president hits out at Real Madrid refereeing 'conspiracy' claims
 MEXC Launches “Real Stocks, Real Friends” with Rewards for Bringing Friends to Wall Street
 Mbappe continues media push for Ballon d'Or recognition
 Stocks rise on AI buzz, oil prices cool
 India narrowly survive huge scare against minnows Japan
 Missing F-35 fighter parts 'not sensitive', says Australia minister
 Cambodia showcases scams crackdown with global conference
 Afghan cyclist who disguised herself as man wins Asian Games silver
 Typhoon Dujuan leaves four dead in Japan, 45,000 houses without power
 G7 leaders condemn Houthi strikes on Saudi Arabia
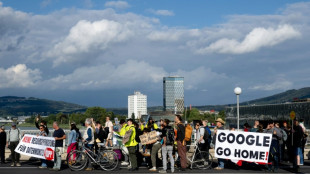 Google data centre sparks protests in Austria
 Shin Ohashi: Junk food-loving teen and Japan's next big swimming hope
 Stocks rise on AI buzz, drop in oil prices
 China's robot dancers limber up for America's Got Talent final
 Despite military might, Saudi struggles to crush the Houthis
 Trump to tout deals, defend Iran war in UN speech
 Sri Lanka to issue verdict in landmark Easter attack trial
 Macron says talks with Trump on Red Sea, Ukraine 'constructive'
 Green policies just good politics, says UK minister
 Bardot auction in Paris fetches nearly one million euros
Britain announced Monday that it has ceded control of bailed-out bank giant NatWest, cutting its stake to below 50 percent for the first time since the global financial crisis.
The government has sold off another tranche of shares for more than £1.2 billion ($1.6 billion, 1.4 billion euros), taking its holding from 50.6 percent to 48.1 percent.
The group was rescued with £45.5 billion of taxpayers' cash in the world's biggest banking bailout at the height of the 2008 meltdown.
"This is a landmark in the government's plan to return to private ownership the institutions brought into public ownership as a result of the 2007-2008 financial crisis," the Treasury said in a statement.
The UK had already returned state-rescued Lloyds Banking Group to full private ownership five years ago.
- 'Important milestone' -
NatWest Chief Executive Alison Rose described Monday's news as an "important milestone".
Britain has sold about 550 million shares at 220.5 pence per share to NatWest, which was formerly known as Royal Bank of Scotland (RBS).
"This sale means that the government is no longer the majority owner of NatWest Group and is therefore an important landmark in our plan to return the bank to the private sector," added Economic Secretary to the Treasury John Glen.
"We will continue to prioritise delivering value for money for the taxpayer as we take forward this plan."
At its peak, the government owned 84 percent of the financial services giant but this has been gradually reduced.
The Edinburgh-based bank was ravaged by its badly-timed consortium takeover of Dutch bank ABN Amro at the top of the market in 2007, just before the financial crisis struck.
RBS has since undertaken a massive restructuring to sell assets, slash its balance sheet and axe thousands of jobs worldwide.
The bank returned to net profit in 2017 after nine straight annual losses.
The group's performance has been blighted, however, by litigation and conduct costs, including compensation for a mis-selling credit insurance scandal.
Rose, the first female CEO of a major UK lender, renamed the bank NatWest in a bid to move on from its troubled past.
In the wake of the pandemic, RBS sank into the red in 2020 after setting aside billions to cover potential Covid fallout.
But NatWest rebounded back into profit last year as the British economy recovered from Covid.
Since 2008, the group has axed its total workforce from almost 200,000 staff to 56,200 in 2021.
And it has dramatically slashed its balance sheet from £2.2 trillion to just £782 billion.
The bank exited 35 nations and currently operates in 19 countries.
- 'Champagne on ice' -
NatWest shares rose 1.9 percent to 224.70 pence in late Monday morning trade on London's rising FTSE 100 index.
However, analysts cautioned about adverse fallout from soaring living costs in home market Britain.
"Natwest is finally free of state control after well over a decade," said AJ Bell investment director Russ Mould.
"Any champagne might have to be put on ice given the challenges facing the bank from the cost-of-living crisis and the risks of mounting bad debts."
J.Fankhauser--BTB