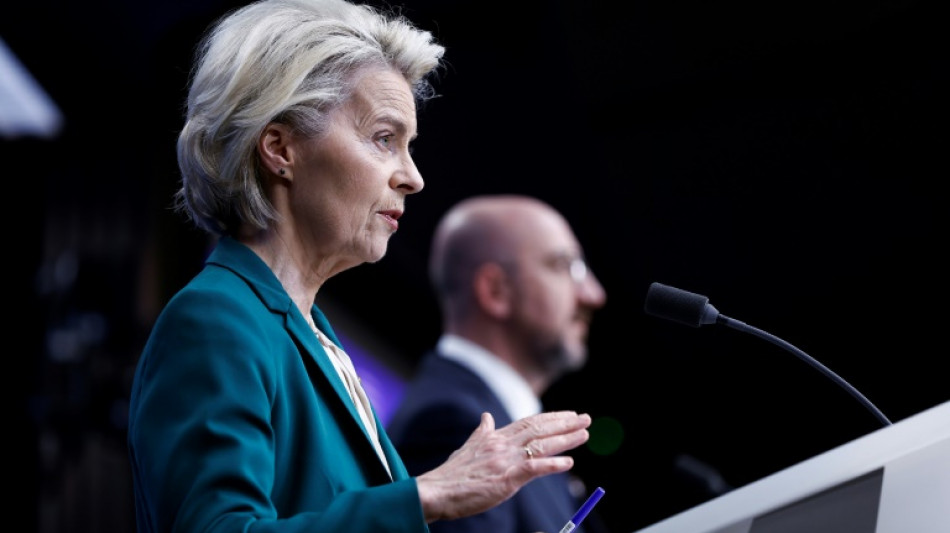
EU seeks to leverage might to confront China, US challenge / Photo: © AFP

 US actress Selma Blair arrested after flight altercation
 One dead as Hurricane Simon creeps along Mexico's Pacific coast
 Carrick's Man United 'hungry and eager' to fix worst start in decades
 Fury as US federal agents search anti-Trump lawmaker's home
 One goal enough for Flick as Barca enter Galatasaray cauldron
 A7 to unveil a service that will re-invent the international payments market
 'Status quo' with EU 'not good enough', UK PM says as summit date set
 Stolen Renoir paintings found behind wall in France
 French supermarkets suffer refrigerator shutdown after 'unprecedented' cyberattack
 Arsenal lose Hincapie and Zubimendi in freak double blow
 Saudi says resilience tested, vows response after deadly airport attacks
 Alcaraz exits Shanghai Masters in straight-sets loss
 Pope to enter hospital on Tuesday for lung operation
 Renshaw shines again before Australia declaration
 Atletico's Simeone encourages goalless Alvarez improvement
 FXGLOBE Rebuilds Its Copy Trading and PAMM Business With B2BROKER's B2COPY
 Nepal rescuers search for missing after flash flood
 Oil rises as Trump comments roil energy markets
 Premier League in limbo as Manchester City soar
 Zelensky vows to respond as Moscow silent on 'energy ceasefire'
 Thousands march in India's capital to demand election chief resign
 African players in Europe: Mbeumo ends goal drought as United draw
 France's high school students plan fresh protests
 NZ bank in free speech row over 'explicit' sheep memes
 China Open champ Zheng withdraws from Wuhan citing fatigue
EU leaders gave fresh impetus on Thursday to a controversial project to integrate the bloc's financial markets in a bid to keep pace with China and the United States -- including in the global race to produce clean technology.
The single market has supported the rise of European giants in different industries, from aviation to chemicals to cars. But at more than 30 years old, the European Union agrees on the need for an update.
During a summit in Brussels, EU leaders were told that the time has come to scale up the single market to include the defence, energy, finance and telecoms sectors.
The argument goes that fragmentation in those sectors with divergent national rules hurts the EU's competitivity, at a time when global powers like China and the United States are pouring billions into state aid to prop up their key industries.
Although the EU has a single currency, the status quo means its start-ups cannot raise the jaw-dropping amounts their US rivals can, and Europeans currently find it more rewarding to send more than 300 billion euros of their savings out of the bloc, mainly into US markets, each year.
"That is money missing for the development of our companies and the European Union. And it is due to the fragmentation of our capital markets," European Commission chief Ursula von der Leyen told reporters after the end of the summit.
The idea of integrating the 27 EU member states' markets, however, divides the bloc, and led to several hours of intense discussions between the leaders.
"There was a very long debate because the starting positions are divergent," French President Emmanuel Macron told a press conference.
"The savings and investment union is the key to being able to mobilise private financing for our priorities. Today, we established a method, principles, a timetable. We will return to the subject from June," Macron added.
- 'No time to waste' -
The EU has a population of 450 million and is home to some of the world's biggest economies including Germany and France.
But while less than 15 percent of personal savings remain in US bank accounts, nearly a third of the 35 trillion euros of European savings are untouched.
German Chancellor Olaf Scholz echoed Macron on the need for progress.
"European companies must be able to benefit from the economies of scale offered by such a large European internal market if we want to progress in terms of growth, competitiveness and successfully complete... the green and digital transition," Scholz said.
The clean energy and digital transitions that Brussels has made its priority in the coming years will require additional annual investment of nearly 620 billion euros ($660 billion), according to the European Commission.
But from artificial intelligence to solar panels, from computer chips to batteries, the EU is fast losing ground on innovation to other global powers.
"There's no time to waste. The gap between the European Union and US in terms of economic performances is becoming bigger and bigger," Enrico Letta, the author of a long-awaited report into the single market, told reporters.
Official EU data shows the bloc's economic stagnation has lasted more than 18 months. While the United States grew by 2.5 percent and China by 5.2 percent in 2023, Eurostat data last month showed the EU economy grew by only 0.4 percent.
- 'Radical change' needed -
The debate comes as the EU seeks to define strategic priorities for the European Commission's next five-year mandate following elections across the bloc in June.
While France insists on greater integration, smaller countries have pushed back against a centralised, European supervision of markets being thrust upon them.
Further headaches stem from suggestions to harmonise taxation and bankruptcy regulations at the EU level -- which have thus far faced insurmountable blocks.
"We must avoid over-bureaucratising, over-regulating and over-centralising everything, which some countries are in favour of," Luxembourg Prime Minister Luc Frieden said.
More than half of the bloc's states expressed reluctance on integrating capital markets during the leaders' talks.
Spurring the sense of urgency is the colossal scale of the sums needed: on top of the hundreds of billions required to fund the green transition, as war rages in Ukraine the EU needs tens of billions of euros more to help Kyiv.
Letta's report is not the only one leaders will be leaning on.
Ex-European Central Bank chief Mario Draghi, increasingly touted as a potential successor to von der Leyen, will present his report on the EU single market in the summer.
Draghi gave a taste of what to expect in a speech this week, when he called for "radical change".
F.Stadler--VB