
Markets sink as US debt talks stall, fuelling default fears / Photo: © AFP/File

 NBA close to picking new $12-13bn Vegas team owners: report
 LA28 Olympics torch relay to visit all 50 states
 Spain brush aside Croatia in Nations League, England down Czechs
 Trump hails 'morally binding' AI self-regulation pledge
 Yamal inspires Spain to Croatia romp on World Cup homecoming
 UN to hold fourth informal poll of secretary-general candidates
 Who are the Emiratis behind crisis-hit Manchester City?
 Singer Angelique Kidjo urges Africans to 'create together'
 Alleged Rihanna mansion shooter mentally fit for trial, says judge
 Mystery over UK airbase scare as police find petrol not explosives
 OpenAI unveils low-cost AI model, a day after shelving Astra upgrade
 Premier League confirms Man City guilty of serious financial breaches
 Brazil's Lula turns to Bad Bunny tune to criticise Trump ahead of polls
 Nigerian dancer eyes world record after seven-day marathon
 Swiss regulator concludes Julius Baer bank probe
 Brazil's patron saint pulled into latest election scrap
 Football overload leaves players near 'breaking point', warns Tebas
 Paris Eiffel Tower says chief to step down after uproar over removing women staff
 Amaze Holdings (NYSE: AMZE) Executes Binding LOI to Acquire BullionFX | Alchemy, a Decentralized Gold-Backed Financial Ecosystem for Valued at US$155 Million
 Clashes between French teens, police as school blockades intensify
 Stocks move sideways despite oil moving lower
 African leaders to gather in Egypt for business summit
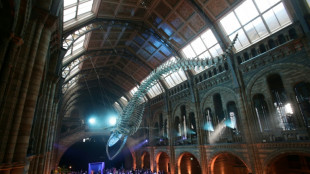 UK decides against charging foreign visitors for museums
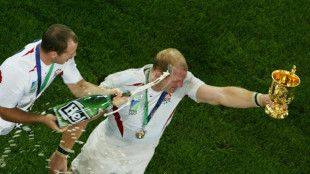 Dallaglio to sell England World Cup winners' medal
 Brazil come from behind to beat Australia 4-2 in friendly
Stock markets tracked losses in Wall Street on Wednesday as investors grow increasingly concerned about stalled US debt ceiling talks aimed at averting a painful default.
The optimism that flowed through trading floors at the start of the week has given way to trepidation, with several Republicans questioning an early June deadline, and some even saying the country is nowhere near running out of cash anyway.
All eyes are now on Washington, where President Joe Biden and House Speaker Kevin McCarthy have had a number of meetings to find a path to lifting the borrowing limit from the current $31.8 trillion.
The two men said Monday that talks had been "productive" and they were confident a deal would be coming.
Republicans have set cutting spending next year to 2022 levels as a "red line", but Democrats have so far refused to commit to that.
On Tuesday, Republican Representative Ralph Norman warned that McCarthy had said the two sides were "not anywhere near close" to an agreement.
The Speaker also tweeted: "With just 9 days left to go, Republicans remain the only ones in Washington who have actually done anything to lift the debt limit and avoid default."
However, White House Press Secretary Karine Jean-Pierre struck a more upbeat tone, saying: "We are seeing movement."
"Both sides have to understand that they're not going to get everything that they want."
Some Republicans have said they do not believe warnings from the Treasury and Congressional Budget Office (CBO) that the coffers are about to run dry.
Treasury Secretary Janet Yellen said an agreement must be reached by June 1 otherwise the United States risks defaulting on its debt repayments, which most economists warn could spark turmoil in the global economy and markets.
The CBO, the Bipartisan Policy Center and banking giants including Goldman Sachs have also pencilled in the first few weeks of next month as the period when the crisis could come to a head.
- 'Manufactured crisis' -
But House Majority Leader Steve Scalise said Tuesday he wanted to "see more transparency on how they came to that date" of June 1.
"It looks like they're hedging now and opening the door to move that date back."
And Texas Representative Chip Roy described warnings of a default as a "manufactured crisis", adding: "The fact is, we're not going to default on our debt.
"That's just completely false. We've got the money to do it."
SPI Asset Management's Stephen Innes said: "Beyond economics, the debt limit debate highlights the political polarisation that persists in the US, and casts a cloud over the political process in Washington.
"The repeated brinkmanship could catch the eye of the rating agencies once again" after S&P downgraded the US credit rating during a similar standoff in 2011.
He added that back then, "the underlying issue was the worsening political polarisation, and it's hard to argue that the process has done anything other than continue to worsen since 2011."
After the sell-off on Wall Street, Asia and European markets were also under pressure on Wednesday.
Hong Kong and Shanghai each gave up more than one percent, while there was also selling in Tokyo, Seoul, Sydney, Taipei, Singapore and Manila, though there were gains in Wellington, Jakarta, Mumbai and Bangkok.
London opened lower as data showed Britain's annual inflation rate fell sharply to an eight-month low of 8.7 percent in April thanks to much weaker energy prices.
Paris and Frankfurt also sank.
Traders are also looking forward to the release of minutes from the Federal Reserve's most recent policy meeting, with hopes for an idea about its plans for next month's gathering.
Falling inflation and worries about the banking sector have fanned bets the US central bank will pause its tightening drive, but recent data pointing to a still-strong jobs market, as well as comments from top officials, have traders worried another hike is on the books.
- Key figures around 0715 GMT -
Tokyo - Nikkei 225: DOWN 0.9 percent at 30,682.68 (close)
Hong Kong - Hang Seng Index: DOWN 1.4 percent at 19,161.43
Shanghai - Composite: DOWN 1.3 percent at 3,204.75 (close)
London - FTSE 100: DOWN 1.0 percent at 7,686.26
Euro/dollar: UP at $1.0783 from $1.0774 on Tuesday
Pound/dollar: UP at $1.2443 from $1.2415
Dollar/yen: UP at 138.60 yen from 138.57 yen
Euro/pound: DOWN at 86.52 pence from 86.74 pence
West Texas Intermediate: UP 1.1 percent at $73.74 per barrel
Brent North Sea crude: UP 1.1 percent at $77.67 per barrel
New York - Dow: DOWN 0.7 percent at 33,055.51 (close)
-- Bloomberg News contributed to this story --
S.Keller--BTB