-
 Messi and Alcaraz love it, now padel takes step closer to Olympics
-
Pope arrives in French border city to speak on united Europe
-
 Tolls mount in Thailand, Myanmar floods
-
The wildfires choking Indonesia, sparking regional haze
-
 Why India's opposition wants top poll official out
-
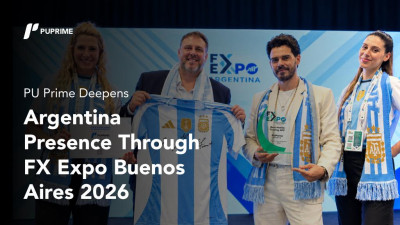
PU Prime Deepens Argentina Presence Through FX Expo Buenos Aires 2026
-
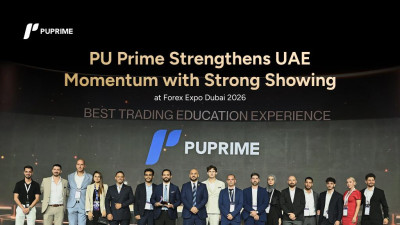 PU Prime Strengthens UAE Momentum with Strong Showing at Forex Expo Dubai 2026
-
Nothing to seal here: NZ police help stranded pup home
-
 Eight dead in Thailand floods since mid-September
-
White House releases list of products US, China could tax less
-
 Oil prices spike after Trump rejects Iran truce offer
-
'Pseudo-journalism': Partisan 'news' sites target US midterms
-
 Taylor Swift sets new record at MTV VMAs
-
'Currently impossible': North Korea defections in freefall
-
 Seoul seeks apology after Ukraine reveals transfer of North Korean POWs
-
Erasmus sizes up 'improved' Wallabies ahead of 2027 World Cup
-
 Messi on target again but Miami downed by Columbus
-
Scandal-weary Brazilians to vote as Lula faces Bolsonaro son
-
 In Washington's political cauldron, a fight over foie gras
-
SpaceX aims to put Starship in orbit for the first time
-
 Flavio Bolsonaro: political heir in his father's shadow
-
Pope to speak on united Europe from French border town
-
 Ravens grab last-second win in Rio as Commanders stop Seahawks
-
Scheffler makes sportsmanship stand over tee screamer
-
 USA rallies to capture 11th consecutive Presidents Cup
-
Anthropic CEO Amodei to dine with Trump at White House
-
 Phillies clinch, Astros wrap up division on final day of MLB season
-
Dupont scores twice to send Toulouse to Top 14 summit
-
 Commanders hand champion Seahawks their first loss
-
Greece stun Klopp's Germany as Ireland show sorrow for Gaza
-
 Dupont scores twice to send Toulouse top of Top 14
-
Ramos fires holders Portugal to Nations League win in Norway
-
 Ireland beat Israel but no handshakes due to war in Gaza
-
Greece hand Klopp first defeat as Germany manager
-
 Tense standoff over flashpoint N.Ireland parade lasts into night
-
Pope promises French sex abuse victims to prevent further harm
-
 Stunned McNulty wins 'miracle' road race world title
-
UK village on edge over threats to air base in terror alert
-
 Re-released 'Avengers: Endgame' snaps-up N. America box office lead
-
Two giant pandas, emblems of China soft diplomacy, arrive in US
-
 American McNulty wins shock road race world title
-
Aleksandar Vucic: from Milosevic minister to long-serving Serbian statesman
-
 Serbia's President Aleksandar Vucic announces resignation
-
Trump expects new Iran talks despite rejecting deal offer
-
 Tuchel urges Bellingham to play with 'rage'
-
Xavi gets first win as Netherlands boss, Denmark beat Wales
-
 Russian strikes on Ukraine kill 8
-
Madrid housing protest camp enters second night as PM vows action
-
 Bavuma, Miller hit centuries as South Africa clinch series
-
Tigray TV station hit by drone, rebels advance in north Ethiopia
US regulators rush to contain SVB fallout, as a second bank fails
US authorities unveiled sweeping measures Sunday to rescue depositors' money in full from failed Silicon Valley Bank and to promise other institutions help in meeting customers' needs, as they announced a second tech-friendly bank had been closed by regulators.
In a joint statement, financial agencies including the US Treasury said SVB depositors would have access to "all of their money" starting Monday, March 13, and that American taxpayers will not have to foot the bill.
The US Federal Reserve, the Federal Deposit Insurance Corporation (FDIC) and Treasury said depositors in Signature Bank, a New York-based regional-size lender with significant cryptocurrency exposure which was shuttered on Sunday after its stock price tanked, would also be "made whole."
And in a potentially major development, the Fed announced it would make extra funding available to banks to help them meet the needs of depositors, which would include withdrawals.
"We are taking decisive actions to protect the US economy by strengthening public confidence in our banking system," the agencies said in their joint statement.
"The US banking system remains resilient and on a solid foundation," due in large part due to reforms undertaken after the financial crisis of 2008 that introduced new safeguards for the banking industry.
"Those reforms combined with today's actions demonstrate our commitment to take the necessary steps to ensure that depositors' savings remain safe."
- Avoiding 'contagion' -
The FDIC guarantees deposits -- but only up to $250,000 per client and per bank.
Federal banking law, however, would allow the FDIC to protect uninsured deposits if a failure to do so would pose systemic risks, the Washington Post reported.
Regulators on Friday took control of SVB -- a key lender to startups across the United States since the 1980s -- after a huge run on deposits left the medium-sized bank unable to stay afloat on its own.
Hours before Sunday's joint statement, Treasury Secretary Janet Yellen said the government wants to avoid financial "contagion" from the SVB implosion, as it ruled out a bailout.
With the bank's future, and its billions in deposits, up in the air, officials from the three agencies raced to craft a solution just hours before financial markets opened in Asia, and to avert a potential financial panic.
Yellen told CBS that the US government wanted "to make sure that the troubles that exist at one bank don't create contagion to others that are sound."
She added that the government was working with the FDIC on a "resolution" of the situation at SVB, where some 96 percent of deposits are not covered by the FDIC's reimbursement guarantee.
Investors punished the banking sector in total on Thursday after SVB disclosed the extent of its troubles the day before, but by Friday, shares in some larger banks posted gains.
Despite attempts by US officials to assure the financial markets, regional lenders remained under pressure.
They included the First Republic Bank, which slumped nearly 30 percent in two sessions on Thursday and Friday, and Signature Bank, which lost a third of its value since Wednesday evening -- and which was shuttered on Sunday.
Amid concerns overseas, Tokyo stocks opened lower on Monday, with the benchmark Nikkei 225 index down 0.92 percent.
- No bailout -
Since Friday, there have been calls from the tech and finance sectors for a bailout.
Yellen said reforms made after the 2008 financial crisis meant the government was not considering this option for SVB.
"During the financial crisis, there were investors and owners of systemic large banks that were bailed out... and the reforms that have been put in place means that we're not going to do that again," she said.
In their joint statement on the latest bank woes and efforts to protect depositors of SBV and Signature, the agencies stressed shareholders and certain unsecured debtholders will not be protected and that senior management has been removed.
Following the 2008 failure of Lehman Brothers and the ensuing financial meltdown, US regulators required major banks to hold additional capital in case of trouble.
US and European authorities also organize regular "stress tests" designed to uncover vulnerabilities at the largest banks.
SVB's implosion represents not only the largest bank failure since Washington Mutual in 2008, but also the second largest failure ever for a US retail bank.
Little known to the general public, SVB specialized in financing startups and had become the 16th largest US bank by assets: at the end of 2022, it had $209 billion in assets and approximately $175.4 billion in deposits.
The company previously boasted that "nearly half" of technology and life science companies that had US funding banked with them, leading many to worry about the possible ripple effects of its collapse.
J.Fankhauser--BTB